TBILLPRICE & TBILLEQ Treasury Bill Formulas
Learn how to evaluate US Treasury Bills in Excel with TBILLEQ, TBILLPRICE, and TBILLYIELD. Convert discount rates to bond-equivalent yields cleanly.

Corporate cash managers and liquidity desks invest idle corporate cash in short-term government debt like US Treasury Bills (T-Bills). Unlike traditional coupon bonds that pay regular interest payments, T-Bills are zero-coupon securities sold at a discount to their $100 face value and redeemed at full par upon maturity.
In money markets, T-Bill yields are quoted on a 360-day bank discount basis, whereas corporate bonds and bank deposits use a 365-day Bond-Equivalent Yield (BEY). Comparing discount rates directly against 365-day yields distorts yield comparisons. Excel provides three specialized formulas for T-Bills: TBILLEQ, TBILLPRICE, and TBILLYIELD.
Quick Comparison: Treasury Bill Functions
| Formula | Input | Output | Trading Purpose |
|---|---|---|---|
TBILLPRICE(settle, mat, disc) |
Settlement, maturity, discount rate | Price per $100 face value | Determining exact cash outlay required to buy the T-Bill. |
TBILLYIELD(settle, mat, pr) |
Settlement, maturity, price | Annualized yield | Calculating realized yield from a secondary market price. |
TBILLEQ(settle, mat, disc) |
Settlement, maturity, discount rate | Bond-Equivalent Yield (BEY) | Comparing short-term T-Bills directly against 365-day bonds and CDs. |
The Strict 365-Day Ceiling
These formulas are strictly engineered for money-market securities with a maturity of one year or less (365 days or fewer) from settlement. If the maturity date exceeds 365 days, Excel immediately throws a #NUM! error.
Hands-on Practice Playground
Use the Treasury Bill issuance schedule below to calculate discount prices and convert discount rates to bond-equivalent yields. Follow each objective to complete the exercise.
In cell E2, calculate the purchase price per $100 for UST-3M-BILL using TBILLPRICE.
In cell E2, calculate the purchase price per $100 face value for UST-3M-BILL using the TBILLPRICE formula with settlement B2, maturity C2, and discount rate D2.
In cell F2, convert the discount rate into a 365-day Bond-Equivalent Yield using TBILLEQ.
In cell F2, convert the 360-day discount rate D2 into a 365-day Bond-Equivalent Yield (BEY) using TBILLEQ with settlement B2, maturity C2, and discount rate D2.
In cell E3, calculate the purchase price for the 6-month T-Bill.
In cell E3, calculate the purchase price per $100 face value for the 6-month T-Bill using TBILLPRICE with settlement B3, maturity C3, and discount D3.
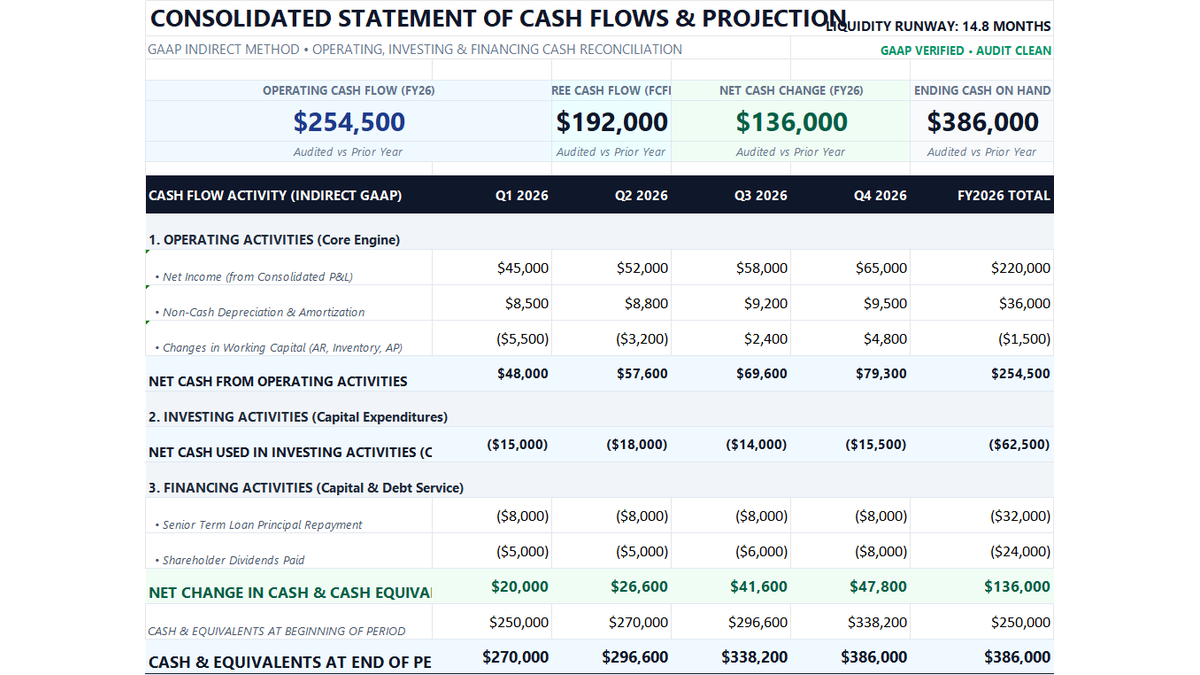
Ready to apply TBILLPRICE & TBILLEQ Treasury Bill Formulas in a real workbook?
Put professional financial formulas into practice inside an executive cash flow model.
Open 12-Month Cash Flow StatementShare This Lesson
Spread the word with your peers and challenge your friends